

Bally’s Corporation is attempting to advance major casino developments in Chicago, New York and Las Vegas while managing a balance sheet that now carries a formal going-concern warning.
The warning appeared in Bally’s quarterly filing for the period ending June 30, 2026. Management said its current forecasts indicate that, without additional financing or other planned transactions, the company may fail to satisfy liquidity and leverage requirements attached to its revolving credit facility during the following 12 months.
That statement does not mean Bally’s has filed for bankruptcy or stopped operating. It means the company has identified material uncertainty about whether its present resources and completed financing arrangements will be sufficient to meet its obligations and remain compliant with its loan conditions.
The distinction is important. Bally’s continues to generate substantial revenue and operate casinos across the United States—remaining a frequent subject of online casino reviews and insights—but revenue, available cash, and money restricted to specific construction projects cannot be treated as interchangeable. Its expansion strategy now depends on whether financing, asset monetization, and property-level performance develop as management expects.
Bally’s Reported A Formal Going-Concern Warning
Bally’s filed its second-quarter Form 10-Q with the Securities and Exchange Commission on August 14, 2026. The filing disclosed that lenders had conditionally waived compliance with the company’s consolidated net-leverage-ratio covenant through a period scheduled to extend into 2027.
The waiver is not unconditional. Bally’s must continue satisfying a minimum liquidity requirement and other provisions attached to its revolving credit facility.
According to the Bally’s second-quarter SEC filing, management’s forecasts did not project compliance with the liquidity-maintenance requirement or the leverage covenant after its reinstatement when planned but unfinished financing transactions were excluded.
Bally’s consequently concluded that the situation raised substantial doubt about its ability to continue as a going concern. The company also said its proposed responses had not been finalized, remained subject to market conditions and depended partly on third parties.
This accounting language is serious, but it requires careful interpretation. A going-concern disclosure evaluates whether sufficient uncertainty exists over the company’s ability to meet obligations during the relevant assessment period. It is not an announcement that Bally’s properties will close or that every development has lost its financing.
The immediate issue is covenant compliance. If Bally’s cannot meet the conditions imposed by its lenders and does not obtain another waiver, those lenders could potentially accelerate debt covered by the credit agreement. That possibility makes liquidity management more urgent than the size of any single casino proposal.
Cash Declined While Debt And Interest Costs Remained High
Bally’s reported $390.2 million in cash and cash equivalents at June 30, down from $798.4 million at the end of 2025. It held another $97.6 million in restricted cash, but restricted balances include funds that are not freely available for general corporate spending.
Long-term debt, including its current portion and after accounting adjustments, stood at approximately $4.51 billion. Total liabilities reached $8.64 billion when leases and other obligations were included.
The company had $195.8 million available through its revolving credit facility at the end of June. Bally’s said availability would be affected by contractual reductions, with the facility’s total capacity scheduled to fall to approximately $319 million in October 2026.
| Financial Measure | Reported Amount At June 30, 2026 |
|---|---|
| Cash and cash equivalents | $390.2 million |
| Restricted cash | $97.6 million |
| Available revolving-credit capacity | $195.8 million |
| Long-term debt, including current portion | $4.51 billion |
| Total liabilities | $8.64 billion |
| Q2 total revenue | $792.2 million |
| Q2 interest expense | $119.0 million |
| Q2 net loss attributable to Bally’s | $146.1 million |
The operating statement shows why revenue alone does not resolve the problem. Bally’s generated $792.2 million in second-quarter revenue, including $608 million from gaming. It nevertheless recorded a $146.1 million net loss attributable to the company.
Interest expense reached approximately $119 million during the quarter and $228.9 million during the first six months of 2026. That six-month interest figure was close to Bally’s reported $247.3 million in adjusted EBITDA for the same period.
Adjusted EBITDA is not the same as cash available to repay debt. It excludes several expenses, including interest, taxes, depreciation and certain development or transaction costs. The comparison nevertheless illustrates how financing costs can absorb a substantial portion of the earnings generated by casino and digital operations.
Chicago Has Dedicated Funding But Still Creates Long-Term Obligations
Bally’s permanent Chicago casino is one of the most advanced projects in the company’s development pipeline. The planned $1.7 billion resort is being constructed at the former Chicago Tribune publishing site along the Chicago River.
The development is expected to replace Bally’s temporary casino at Medinah Temple. Plans have included a 500-room hotel, approximately 3,400 gaming positions, restaurants, an entertainment venue and public space.
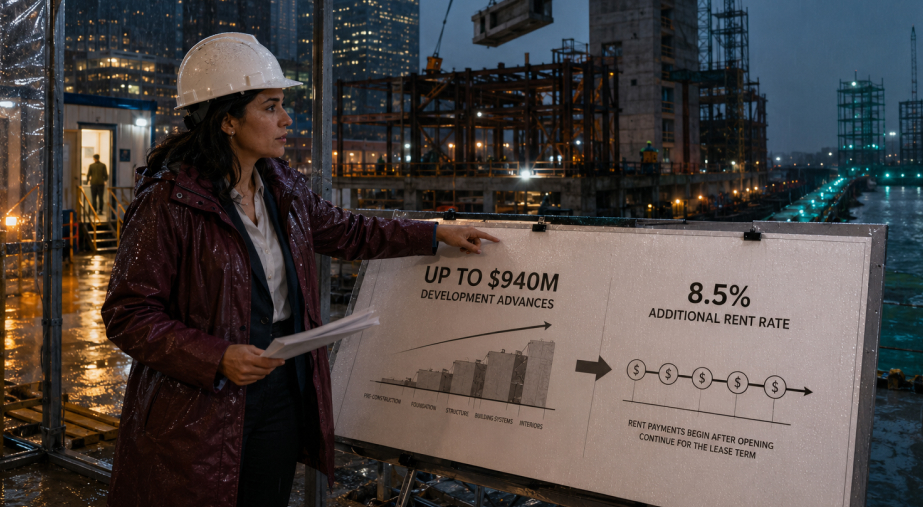
Bally’s has secured a project-level funding structure with Gaming and Leisure Properties, commonly known as GLPI. Under that agreement, GLPI committed to provide as much as $940 million for qualifying hard construction costs.
During the first six months of 2026, Bally’s received approximately $274 million in reimbursements for Chicago construction expenditure. That financing makes Chicago different from an entirely unfunded proposal.
However, GLPI’s money is not cost-free corporate liquidity. The arrangement increases the rent Bally’s must pay under its master lease. Additional rent is calculated at 8.5% of the development advances provided to the company.
Bally’s also remains subject to its agreement with the City of Chicago. Its filing said the relevant subsidiary must spend at least $1.34 billion on the temporary casino and permanent resort, with approximately $400 million of that commitment remaining as of June 30.
The company expects total development costs to exceed the minimum contractual amount. It could not yet reasonably estimate the excess because some underlying contracts had not been completed.
Chicago therefore demonstrates the difference between having construction financing and eliminating financial risk. Dedicated funding can help complete a building, but the resulting lease payments, operating costs and revenue requirements continue after construction ends.
The Bronx Project Adds A Different Financing Test
Bally’s Bronx proposal represents another multibillion-dollar commitment, but it is at a different stage from Chicago.
The company secured one of New York’s downstate commercial casino licenses for a planned resort at Bally’s Golf Links at Ferry Point. Bally’s paid a $500 million New York gaming-license fee during the first half of 2026 and also recorded an obligation connected to its acquisition of land assets at the site.
The proposal has been valued at approximately $4 billion. Plans have described a casino, hotel, entertainment venue, dining, parking and improvements to the surrounding property.
In July, Bally’s executed a nonbinding term sheet for a loan intended to support further development of the Bronx property and general corporate purposes. A term sheet can establish the principal conditions under discussion, but it is not equivalent to a closed loan with money available for use.
That distinction sits at the center of Bally’s liquidity disclosure. Management identified the Bronx financing as one of several possible measures, alongside asset monetization, an equity sale and other debt financing. The company simultaneously acknowledged that those measures were unfinished and could not yet remove the going-concern uncertainty.
Bally’s has already committed meaningful capital to New York through its license payment and land position. The next question is whether it can convert the proposed loan into binding financing on terms that do not place excessive additional pressure on the wider company.
A casino license can create a valuable development opportunity, particularly in a restricted market such as New York City. It also introduces deadlines, construction obligations and the risk that significant capital must be deployed before the finished property begins producing gaming revenue.
Las Vegas Remains The Least Defined Major Development
Bally’s controls development rights at the former Tropicana Las Vegas site, where the Athletics are constructing a separate Major League Baseball stadium.
The company has discussed an integrated resort costing approximately $1.2 billion. Early concepts have included a casino, hotel rooms, dining, retail and entertainment surrounding the ballpark site.
Las Vegas could give Bally’s a prominent property at the intersection of Las Vegas Boulevard and Tropicana Avenue. Stadium visitors might support casino, hotel and restaurant demand, while an integrated resort could give the site activity beyond baseball games.
The project remains less financially defined than Chicago. Bally’s has not presented the same completed construction-funding arrangement supporting the permanent Chicago casino.
Timing also matters because the Athletics’ stadium and Bally’s resort are separate projects. Progress on the ballpark does not guarantee that the surrounding casino development will open simultaneously or in its originally presented form.
This uncertainty does not make the Las Vegas proposal impossible. It means renderings and estimated development costs should not be interpreted as evidence that the complete financing package, construction schedule and final amenity program are settled.
The former Tropicana site remains strategically valuable. Bally’s must determine how to preserve that opportunity without allowing another large development to intensify its immediate liquidity requirements.
Rising Revenue Does Not Eliminate Balance-Sheet Risk
Bally’s financial position comes during a period of overall growth for regulated U.S. commercial gaming.
As gclubgod.com recently reported, U.S. commercial gaming revenue reached $20.39 billion in Q2 2026, rising 5.1% from the same quarter one year earlier. Traditional casino gaming remained the industry’s largest component, while regulated iGaming recorded the fastest percentage growth.
A growing national market can support Bally’s existing casinos and improve the potential audience for future resorts. It cannot guarantee that each project will produce returns sufficient to cover its construction, financing and lease obligations.
Casino revenue is also not evenly distributed. Mature properties can face slower growth, new competition or higher operating costs even when the national industry reaches a record. A new resort may need several years to stabilize after opening, particularly when it enters a competitive urban market.
Bally’s digital operations provide another channel, but they do not automatically finance physical expansion. North America Interactive produced approximately $3 million in adjusted EBITDAR during Q2, while the much larger Intralot-related operations have their own financing structures and obligations.
The company specifically noted that Bally’s Intralot does not guarantee Bally’s Corporation debt. Its financing cannot therefore be treated as an unrestricted reserve available to cure every covenant issue elsewhere in the group.

Bally’s Has Several Possible Liquidity Measures
Management is pursuing multiple responses to the disclosed pressure.
Asset monetization could provide cash by selling property or another investment. Sale-leaseback transactions can also release capital tied to real estate, although they replace ownership with continuing rent obligations.
Bally’s used that model at Twin River Lincoln Casino Resort in Rhode Island. During the first half of 2026, it received $685 million in sale-leaseback proceeds while paying a $500 million New York license fee.
An equity sale could strengthen liquidity without adding conventional debt, but it could dilute existing shareholders or require terms reflecting the company’s current risk. Additional borrowing would provide funds more directly while also increasing interest costs and potentially adding security or covenant requirements.
Bally’s also entered into $1.1 billion of senior secured term loans in February 2026. Those loans carry a comparatively expensive interest structure: term SOFR with a 3% floor plus a 7.5% margin, or an alternative base rate with the same floor plus 6.5%. The company can elect to pay a portion of the interest in kind, which conserves current cash but increases the amount owed.
In its official second-quarter results announcement, Bally’s presented its operating performance and development activity alongside the financial statements. Investors and regulators will now need to measure subsequent announcements against the more cautious assumptions contained in the SEC filing.
The strongest resolution would involve more than obtaining a short extension. Bally’s needs enough durable liquidity to satisfy its lenders while completing priority projects without repeatedly depending on unfinished transactions.
A Going-Concern Warning Is Not A Casino Closure Announcement
The severity of the disclosure should not be understated, but neither should it be exaggerated.
A company can resolve a going-concern issue through completed financing, asset sales, covenant amendments, stronger cash generation or reduced spending. Bally’s continues operating a large casino portfolio, and lenders may prefer an amended agreement over an accelerated repayment that creates disruption for every party.
At the same time, the language cannot be dismissed as routine. Bally’s management explicitly concluded that its plans did not yet alleviate substantial doubt because they were not finalized and remained outside the company’s complete control.
The market reaction showed how seriously investors treated that uncertainty. Bally’s shares fell 26% on the first trading day after the filing, according to The Wall Street Journal’s analysis of the company’s expansion pressure.
Casino customers should not interpret the stock decline as evidence that balances, rewards or individual properties have automatically become unavailable. Operators remain subject to state gaming rules, and player funds or regulated obligations may receive treatment different from ordinary corporate cash.
For cities hosting Bally’s developments, the more relevant concern is project execution. Chicago, New York and Las Vegas need to distinguish money committed to construction from general liquidity, monitor development milestones and ensure that public promises are supported by enforceable agreements.
Bally’s Next Financing Decisions Will Define Its Expansion Strategy
Bally’s is not facing a shortage of development opportunities. Its challenge is deciding how many opportunities its balance sheet can support at the same time.
Chicago has substantial GLPI construction funding but carries escalating rent and remaining development obligations. The Bronx offers access to a restricted New York City casino market but requires a proposed loan to become binding. Las Vegas provides a valuable destination site but remains the least defined of the three major developments.
The company entered the second half of 2026 with $390.2 million in unrestricted cash, approximately $4.51 billion in long-term debt including the current portion, and a revolving-credit waiver conditioned on maintaining liquidity.
Those figures place financing—not casino demand—at the center of the immediate story.
If Bally’s completes its planned transactions on workable terms, the present warning may become a temporary stage in a complicated expansion program. If financing is delayed, too expensive or smaller than expected, the company may need to sell assets, reduce project scope, change construction timing or negotiate further relief with lenders.
The next meaningful milestone will therefore not be another resort rendering or projected job count. It will be evidence that Bally’s has converted its proposed financing measures into completed transactions capable of supporting both its existing casino operations and its development commitments.


